They laughed at eight dollars. Then the account told the truth. An old man walked into the bank asking for a small withdrawal, the kind most people would never notice. The teller smirked, the manager dismissed him, and the room quietly judged what they thought was poverty. But one screen changed everything. Hidden behind that tiny request was a $41 million client record, a private history, and a fortune the staff had ignored until it was too late. This wasn’t just a bank mistake. It was the moment respect became the most expensive thing in the room.
An old Nebraska farmer calmly requested eight dollars, and the bank treated him like an inconvenience downtown that cold day. They judged his mud-stained boots, ignored his savings book, and sent him outside while customers watched in silence close by. A janitor’s ten-dollar kindness revealed the dignity everyone else had overlooked, then uncovered forty-one million dollars tied to that branch. The farmer could have emptied his accounts, but he investigated first and discovered neighbors facing the same disrespect across town. What happened next forced a powerful bank to refund fees, reopen farm loans, retrain staff, and rethink who deserved respect.
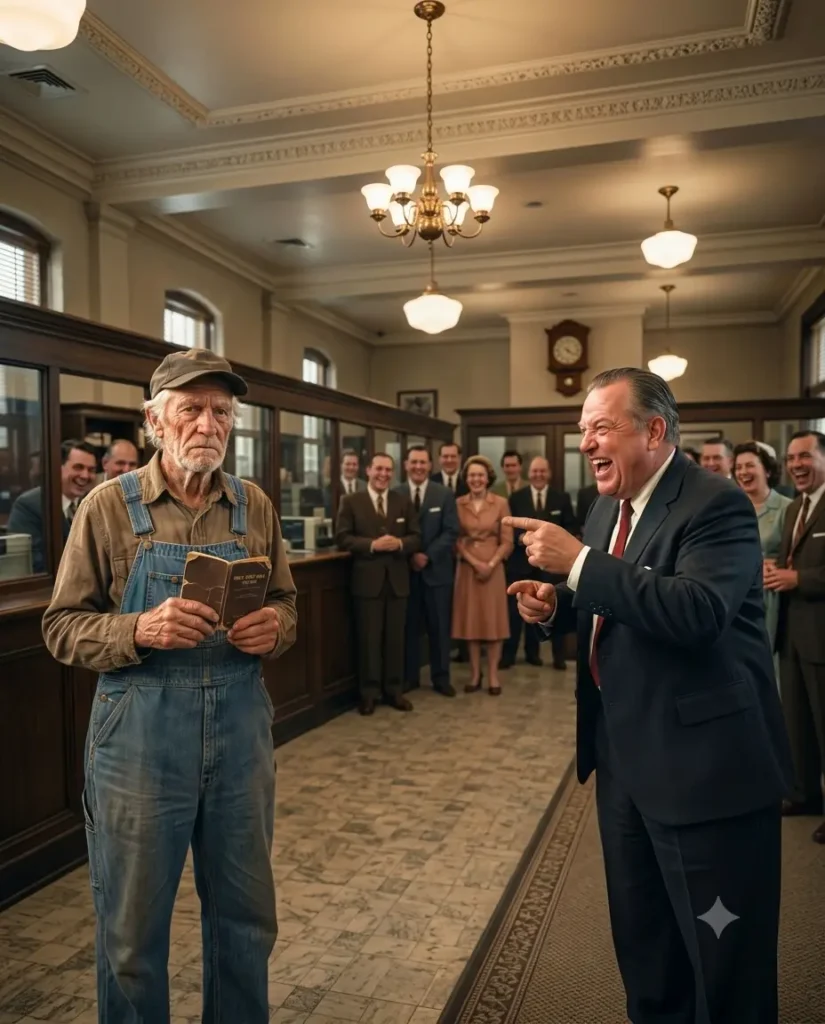
No one inside Prairie State Bank in North Platte, Nebraska, suspected that Thursday morning would change its branch. A thin elderly farmer crossed automatic glass doors, his faded coat contrasting against polished floors and white lights. Several customers noticed dried mud on his boots, then returned their attention to phones and paperwork. He approached the counter, removed a worn savings passbook, and laid it carefully before the teller. He introduced himself as Samuel Rourke and asked to withdraw exactly eight dollars from his savings. A few waiting customers turned toward him, surprised anyone would visit the branch for so little money. To them, it looked like a trivial errand, inconvenient to the staff and unworthy of attention. They had no idea the quiet farmer controlled more than forty-one million dollars in assets. By afternoon, the bank would face the possible departure of assets built across several generations. For Samuel, however, the morning began with an eight-dollar gap between him and medicine.
He lived on 287 acres outside Sutherland, where wheat fields and cattle stretched beneath a restless Nebraska sky. His wooden farmhouse leaned slightly, and patches of different ages covered the barn’s weathered roof. Fence posts tilted in prevailing winds, but Samuel checked each line himself before breakfast. He tended a modest cattle herd, planted wheat, and watched every piece of machinery on his land. When a tractor failed, he reached for tools before considering whether a repair shop might help. His hands were permanently rough, marked by oil, soil, and decades of fixing what others replaced. Neighbors saw him in an old pickup, wearing a brown coat and boots that carried the fields into town. He rarely visited North Platte and spent little on himself, which encouraged people to underestimate him. He never corrected those assumptions or mentioned the business interests connected to his family’s land. To Samuel, being useful mattered more than appearing wealthy to people he barely knew.
If a truck still started, he saw no reason to trade it for newer chrome. If his coat held warmth, he kept wearing it through another winter. Money from good harvests belonged to future repairs, poor seasons, or emergencies his neighbors could not predict. His late wife, Evelyn, had shared that habit and helped him buy farmland when prices were low. Together, they saved carefully, reinvested profits, and rented some fields to neighboring agricultural operations. The farm visible from the county road represented only a portion of their accumulated holdings. Samuel never treated those assets as proof that he mattered more than anyone else. He believed money served best when it protected a family, repaired a farm, or steadied a difficult year. He had no desire to impress strangers with a truck or coat they would forget tomorrow. That belief had shaped his life long before anyone at the bank noticed him.
That morning, he was exactly eight dollars short after paying the remaining cost of a prescription and groceries. He could have asked the grocer to wait for payment, but debt made him uncomfortable. Instead, Samuel decided to withdraw his own money from the bank his family had trusted for decades. His old debit card had expired, and its replacement had not yet arrived in the mail. He slipped the passbook into his coat after repairing a tractor before dawn. Dark grease still marked his palms when he climbed into the pickup and turned toward town. The drive from his farm took thirty-five minutes along open roads pitted by freeze-thaw and farm traffic. Cold wind crossed the plains, rocking the old truck whenever it passed a drainage ditch. Samuel planned to withdraw eight dollars, buy what he needed, and return to his unfinished chores. He had no idea that a small transaction would expose a larger conflict between the bank and its community.
When he entered, mud from his boots left several faint marks across the polished lobby floor. Two customers in business suits glanced downward and shifted away without saying a word. Samuel noticed, but he kept moving toward the counter with his passbook held carefully. The teller, Emily Hart, studied his faded coat and the old book before looking impatiently at him. She asked what he wanted without checking his account or requesting identifying information. He placed the passbook on the counter and made his modest request in a steady voice. Emily paused, then said the branch did not handle withdrawals that small at teller windows. She told him to use an ATM or return when he needed more cash. She had not opened the account or read the balance written inside his passbook. Because the request seemed small, she had decided it was not worth her time.
Samuel explained his debit card had expired and a replacement had not reached his farmhouse. He added that the account had been open for decades without any similar restriction. Emily repeated that other customers were waiting and accused him of slowing down the branch. He remained polite, asking her to review the account before refusing a longtime customer. People near the waiting area began turning to watch the exchange. A quiet laugh came from one chair, followed by a man shaking his head. Another customer looked at Samuel’s weathered coat, then quickly turned away. Samuel did not raise his voice or accuse anyone of disrespecting him. He pushed the passbook a few inches closer and repeated that the account belonged to him. Emily’s expression tightened as she suggested he ask a relative for help using banking services.
Samuel fell quiet, then asked to speak with the person responsible for the branch. He wanted to know whether the bank truly treated its customers this way. A moment later, Bruce Kessler, the branch manager, emerged from a glass office near the hallway. Bruce wore an expensive charcoal suit and repeatedly checked his watch while the teller explained. He never picked up the passbook or asked an employee to look inside it. His eyes settled instead on mud dried around Samuel’s boots. He asked why an eight-dollar withdrawal required the manager’s attention. Samuel kept his voice even and asked whether the money in the account belonged to him. Bruce acknowledged that it did, then said the bank determined which services employees should provide. He added that employees should not waste time on transactions too small to matter.
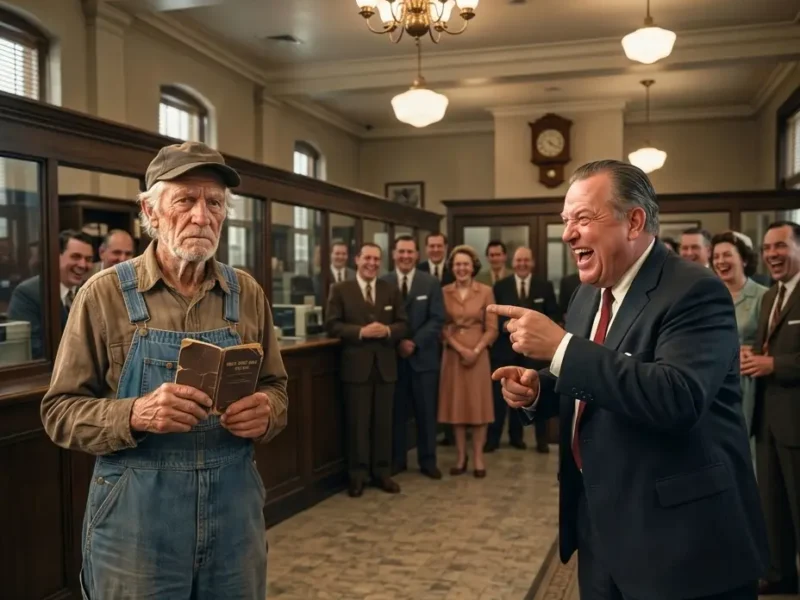
Loud enough for waiting customers to hear, Bruce suggested this bank might not suit someone like Samuel. Several people looked over, while others lowered their eyes or pretended to read their screens. Samuel let the silence settle before asking whether they were refusing eight dollars of his money. Bruce answered yes without hesitation and said the decision was final. That answer told Samuel more than a written policy could have explained. When he stayed in place, Bruce signaled security guard Marcus Lee from across the lobby. Marcus approached and said the bank would not process the withdrawal, so Samuel needed to leave. Samuel did not resist, argue, or make the situation more difficult for the guard. He returned the passbook to his coat and straightened its worn collar. Dozens of customers watched as he crossed the floor and stepped into the parking lot.
Outside, a cold gust moved across the lot while Samuel stood beside the old pickup. The refusal hurt, but the crowd’s silence made the experience feel far more personal. Nobody asked why a bank would deny a customer access to his own money. Some had watched with amusement, while others moved aside as if Samuel had caused trouble. Inside, staff returned to their tasks, and the branch appeared to resume its usual rhythm. Emily joked that the old farmer probably had less than twenty dollars in his account. Near the far hallway, however, janitor Grace Nolan had witnessed the entire exchange. Grace did not know Samuel or how much money he owned. She only knew that the staff had treated an ordinary request with needless contempt. After a few minutes, she slipped through a side entrance and found him still waiting.
Grace reached into her pocket and held out a ten-dollar bill for his medicine. Samuel looked at the money, then at the stranger who had followed him into the wind. For several seconds, he seemed unsure how to respond to an act so simple. He asked why she would help somebody she had never met. Grace explained that she did not have much, but recognized how people judged working clothes. She knew the feeling of being dismissed before anyone bothered to learn your name. Samuel accepted the bill, kept exactly eight dollars, and offered the remaining two back. Grace took the change only after he insisted she keep it. Before she returned inside, Samuel asked how long she had worked at the bank. Grace answered that she had been there long enough to know kindness should not be rare.
When Grace reentered, Samuel stayed beside his pickup and considered what had happened. The anger was fading, but disappointment brought back an old promise his family remembered. For decades, the bank had promised to treat customers fairly, regardless of account size. He pulled an old phone from his coat and called Calvin Price, his family wealth manager. Samuel asked Calvin to review every deposit, certificate, investment account, and farm operating fund he controlled. Calvin checked the records while Samuel waited, watching wind bend the dry roadside grass. The total was more than forty-one million dollars, spread across multiple accounts and holdings. It had accumulated slowly through farmland, investments, and a family business built over generations. His farm was only one visible piece of the resources he and Evelyn had gathered. The bank that refused eight dollars managed most of those financial assets.
Samuel did not order the money moved immediately, even after learning the total. His family had banked there since previous leaders ran the institution. He asked Calvin to review fees, contracts, service agreements, and policy changes from recent years. He wanted to know whether one employee had made a mistake or the bank had changed. That afternoon, preliminary findings raised concerns about how smaller farm accounts were being handled. Fees had increased, while applications for seed, equipment, and drought support were delayed. The branch increasingly prioritized customers whose accounts brought larger profits. Small withdrawals and lower-value farm loans received little attention from staff. Samuel asked Calvin to keep examining records before drawing conclusions. He also began calling farmers and shop owners he knew around Lincoln County.
He did not tell them about his forty-one million dollars or threaten the bank. He simply asked whether the branch had served them fairly in recent years. One farmer described a tractor repair loan that arrived after planting season was nearly over. A widow said she had visited repeatedly to correct a fee she should never have paid. A rancher recalled staff losing interest as soon as his requested loan seemed too small. Another family had received no clear answer about a short-term seed loan. Their stories formed a pattern no single customer could easily see. Smaller account holders often felt as if their business mattered less. Samuel realized the morning’s insult was one visible sign of a broader problem. That evening, he decided the bank needed an opportunity to correct it.
He asked Calvin to prepare papers transferring most assets elsewhere, but he held back his signature. Before deciding, Samuel wanted to give the bank time to make meaningful changes. He did not want ordinary employees losing their jobs because a few leaders had failed. His purpose was not revenge, and he had no desire to destroy a local institution. He wanted the bank to examine how it served the community that kept it operating. The following morning, regional executives received notice that a major client was considering leaving. The notice requested preservation of security footage from the previous day’s lobby encounter. It included a formal complaint detailing the refusal to release eight dollars from savings. The incident could no longer be dismissed as a misunderstanding between one teller and one customer. Before long, the phone in Bruce’s office rang repeatedly with questions from the regional team.
Bruce initially insisted that the complaint misunderstood what had happened at his branch. Then regional staff told him Samuel controlled more than forty-one million dollars in bank assets. His expression changed as he finally ordered employees to examine the account records. They found decades of deposits and financial relationships no one had bothered checking. Samuel, however, did not return to embarrass the teller or manager. He sent three requests through Calvin and the regional office. First, the branch should review how it treated customers making small transactions. Second, leaders should examine the fees and farm loan cases that had caused hardship. Third, no customer should be judged by clothing or the amount deposited or withdrawn. A regional investigation team arrived in North Platte that same week.
Security footage showed staff refusing to inspect Samuel’s passbook before rejecting his request. It also recorded Bruce speaking dismissively and signaling the guard. The footage confirmed Samuel had remained calm and caused no disturbance. Investigators also reviewed complaints, fee schedules, loan files, and branch performance targets. They found that bonuses rewarded attention to larger accounts and profitable services. Employees had gradually learned to treat smaller transactions as work with little value. That incentive did not excuse the humiliation, but it helped explain the pattern. The bank suspended Bruce while the review continued and questioned other employees. Samuel asked representatives not to punish every worker who had no part in the incident. He believed accountability should leave room for people to learn and improve.
After the review, Bruce was removed from his role managing the North Platte branch. The bank required him to complete retraining before considering another position. Emily received formal discipline and had to complete customer service training. Employees uninvolved in the confrontation kept their jobs, as Samuel had requested. The bank reviewed hundreds of customer accounts and agricultural loan files across the region. It refunded incorrect fees and reopened several delayed applications for farm financing. A dedicated service counter was created for older customers and people unfamiliar with ATMs. The branch also changed performance measures that had rewarded staff for ignoring small requests. One change followed another, gradually reshaping how employees served the surrounding farming community. For the first time, the bank had to measure trust as carefully as profit.
Samuel later learned Grace wanted stable work but had never had a chance to study banking. He asked the bank to fund training, saying her kindness deserved an open door. He also insisted she earn any new position through effort and demonstrated ability. Grace accepted the opportunity and studied after her janitorial shifts ended each evening. Nearly two years later, she joined the branch as a full-time customer service employee. She never forgot running outside with ten dollars because she feared Samuel lacked medicine. The farmer kept the original eight dollars in an envelope at his farmhouse. He called it the smallest amount he had ever received and one of the most meaningful. By then, the bank had fulfilled enough of its promises to restore some confidence. Samuel chose to keep part of his assets there while moving others to reduce risk.
He said destroying a community bank would have been easy, but helping it improve mattered more. His daily life remained unchanged when he returned to the farm outside Sutherland. He drove the same pickup, checked fences before breakfast, and repaired equipment whenever possible. Neighbors now knew about his wealth, but Samuel remained indifferent to their surprise. He cared more that farmers could enter the bank without feeling unimportant or ashamed. Several months later, he walked through those same glass doors with his old passbook. He approached the counter wearing the same weathered boots and asked to withdraw eight dollars. This time, employee Grace checked the account, completed the transaction, and thanked him respectfully. Samuel carried the cash directly to a local food assistance fund and donated it. The donation represented a choice to return kindness to people who might need it next.
The story had never been about eight dollars or forty-one million dollars. It was about the assumption that small requests came from people with little value. Samuel understood that a worn coat revealed nothing about someone’s character, history, or circumstances. A simple teller transaction should not require wealth to earn ordinary respect. Grace saw a neighbor in trouble where others saw an inconvenience. The bank changed because one person insisted its treatment of customers deserved scrutiny. A local farmer’s quiet complaint eventually improved services for families across the county. His money gave the complaint reach, but his restraint helped keep the response focused on repair. He remembered the ten-dollar bill as much as the millions under management. The final lesson remained simple: dignity should never depend on the clothes someone wears or a number on a screen.
THE END!
Disclaimer: Our stories are inspired by real-life events but are carefully rewritten for entertainment. Any resemblance to actual people or situations is purely coincidental.
Disclaimer : This content may be created by AI for entertainment purposes. Any resemblance to real persons, events, or places is coincidental.